
How locking a below-market rate for your buyers protects your price, widens your buyer pool and moves inventory faster than a discount.
Ask any builder what's slowing sales right now and you'll hear the same answer: it isn't the house, it's the payment. Buyers walk the model, love the floor plan, then run the numbers at today's mortgage rates and walk away. The usual fix is a price cut or a round of incentives. There's a better tool, and the largest builders have been using it for years: the forward commitment.
What is a forward commitment?
A forward commitment is an agreement where a builder reserves a pool of mortgage money at a fixed, below-market interest rate before the buyers are even under contract. Any qualified buyer who finances through the program and closes inside the commitment window gets that rate, no matter where the market moves in the meantime.
Think of it as buying your buyers' rate in bulk. Instead of negotiating a one-off buydown on every contract, you set the rate once, put it on your signs and listings, and sell every home in that phase on a payment buyers can actually afford.
Why the payment matters more than the price
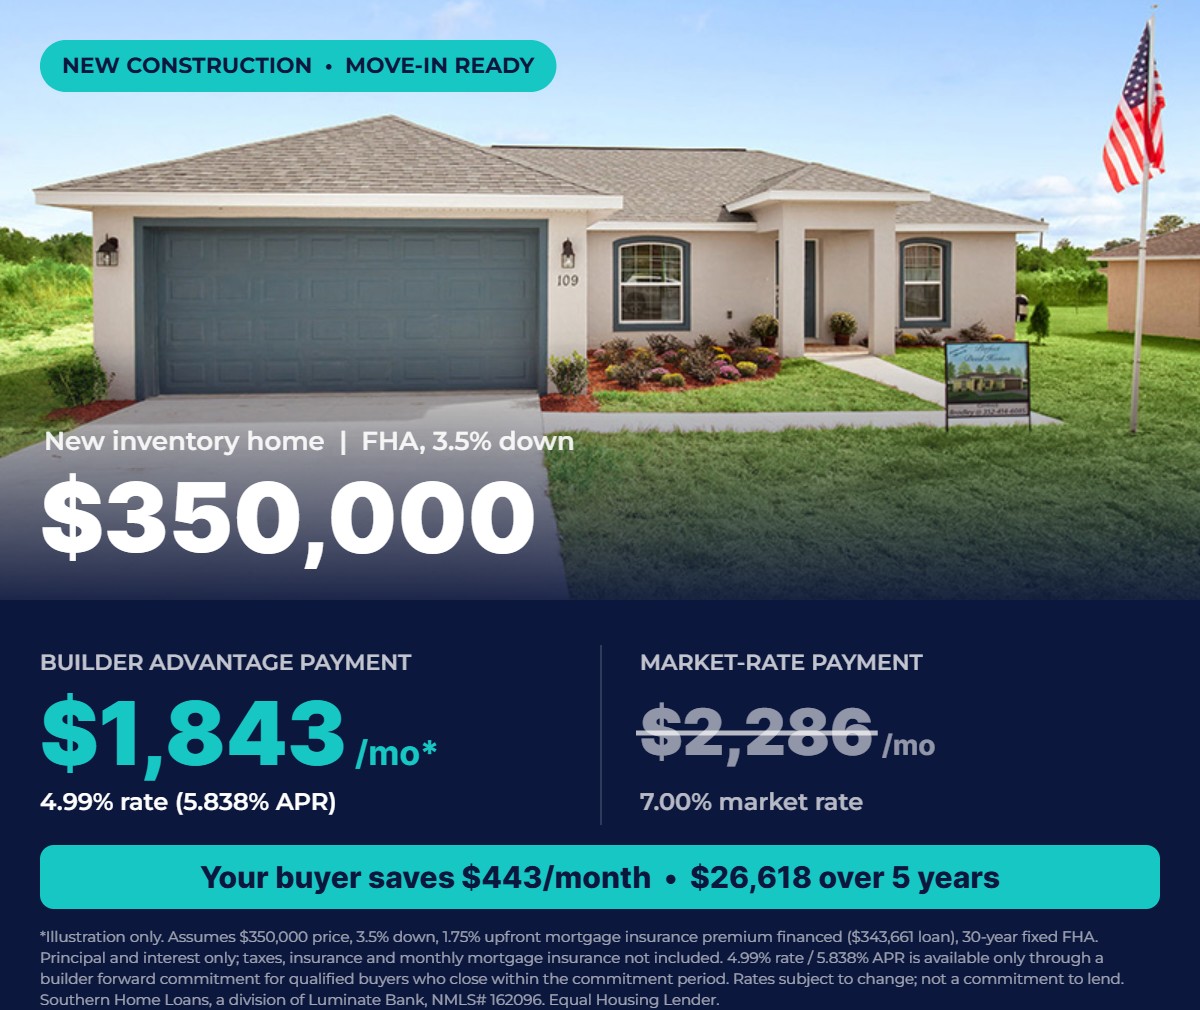
Most buyers shop by monthly payment, not sticker price. A lower rate does more for that payment than almost any price reduction you can reasonably offer. Here's the same $350,000 new home, FHA with 3.5% down, at a 7.00% market rate versus our Builder Advantage rate of 4.99% (5.838% APR)*.
| Market Rate | Builder Advantage Rate | |
| Interest Rate | 7.00% | 4.99% (5.838% APR)* |
| Loan Amount (incl. UFMIP) | $343,661 | $343,661 |
| Monthly Principal & Interest | $2,286 | $1,843 |
That's about $443 a month back in your buyer's pocket, roughly $5,300 a year and more than $26,000 over five years.** To get the same payment with a price cut at 7.00%, you'd have to drop the price by roughly $68,000. A forward commitment typically costs a fraction of that.
Six ways a forward commitment gives builders an edge
1. You protect your price and your comps
Every price cut becomes a comparable sale. Drop one home by $40,000 and the next appraisal in your community has to account for it, which puts pressure on every home you have left to sell. A forward commitment keeps your list price intact, so your comps, and your margins on the rest of the phase, hold up.
2. You qualify more buyers
Lenders qualify buyers on debt-to-income. A lower rate lowers the payment, which lowers the ratio. Buyers who were just over the line at market rates can suddenly qualify for your home. That opens your community to first-time buyers, young families and households that would otherwise be shopping resale or renting another year.
3. Your incentive dollars go further
Pooled pricing on a commitment usually costs less per buyer than buying down rates one loan at a time, and it delivers a far bigger payment reduction than the same dollars spent on a price cut. You're spending marketing money where buyers feel it every single month.
4. You keep your seller concessions
Through our Builder Advantage Program, the forward commitment does not count toward FHA's 6% seller concession limit. You can still contribute up to an additional 6% toward your buyer's closing costs and prepaids, so you can offer a low rate and help with cash to close.
5. Spec homes move faster
A move-in-ready home with a locked low rate creates real urgency. "Buy now and get 4.99%" is a reason to act this month instead of waiting to see what rates do. That turns inventory carrying costs into closings.
6. Less fallout during construction
When a buyer is under contract on a home that won't be finished for months, rate swings are a real risk. If rates jump, the buyer may no longer qualify or may get cold feet. With a forward commitment, buyers keep the committed rate as long as they close inside the window, so your pipeline is more predictable.
Forward commitment vs. temporary buydown vs. price cut
- Price cut: Lowers the payment a little, permanently lowers your comps, and can't be undone.
- Temporary buydown (like a 2-1): Lowers the payment for the first year or two, then the buyer's payment steps up to the full note rate. Buyers still have to qualify at the full rate on many programs.
- Forward commitment: A below-market fixed rate for the full 30-year term on eligible loans, marketed across your whole community, without touching your list price.
How the Builder Advantage Program works
- Reserve your rate. We size a commitment to your realistic closings over your next build cycle, so you only reserve what you're likely to use.
- Market the payment. Put the rate on your signs, listings and model-home materials. We provide co-branded flyers, social ads and payment comparisons.
- Close with confidence. Buyers work with one lender and one point of contact from contract to closing.
The Builder Advantage rate is available on 30-year fixed FHA, VA, USDA and conventional loans, and the program is available to builders nationwide, not just here in Florida.
Is a forward commitment right for your next phase?
If your buyers love your homes but stall at the payment, if you're sitting on spec inventory, or if you're weighing another round of price cuts, it's worth running the numbers. I'll price a commitment against your expected closings and show you exactly what it costs compared with a price reduction on the same homes.
Learn more about the Builder Advantage Program for builders, see the buyer-facing program details, or call me directly at 352-622-1521.
*Rate of 4.99% with 5.838% Annual Percentage Rate (APR) is for a 30-year fixed FHA purchase loan and is available only through a builder forward commitment for qualified buyers who close within the commitment period. Rates, terms and availability are subject to change without notice and are not a commitment to lend. All loans subject to credit approval, underwriting guidelines and property eligibility. FHA loans require an upfront and annual mortgage insurance premium. Payment examples do not include taxes and insurance; actual payment will be higher.
**Illustration only. Assumes $350,000 purchase price, 3.5% down payment, 1.75% upfront mortgage insurance premium financed, 30-year fixed term, 7.00% market rate for comparison. Principal and interest only; taxes, insurance and monthly mortgage insurance not included. Southern Home Loans is a division of Luminate Bank, NMLS# 1281698. Equal Housing Lender. Member FDIC.
Branch Manager at Southern Home Loans · NMLS# 162096. Questions about this article? Call 352-622-1521.
Talk to a loan officer
Tell us a little about your plans and a loan officer will reach out with options and rates. No obligation.
Prefer to talk? Call 352-622-1521 or apply online.